
Budget method · family of four
Build a Southeast Asia family budget that survives contact with real life
A useful relocation budget has three layers: recurring life, first-year setup and money you do not plan to spend. This guide shows how to build all three without disguising guesses as averages.
Last verified 31 August 2026
The short answer
What number should you start with?
Use the five-country envelope—£1,600–£5,500+ a month—only to choose where to investigate. Your decision budget must then replace the country range with a named school, a workable home-school route, a health plan and the exact immigration basis for every family member.
Three pots, three jobs
Do not force the whole move into a monthly number
Separating these pots prevents a healthy monthly cash flow from hiding an unaffordable first year—or a move with no route home.
Recurring life
Rent, school sinking fund, food, transport, insurance, utilities, activities and predictable admin.
First-year setup
School entry fees, rental deposits, temporary housing, flights, documents, immigration and household setup.
Emergency reserve
Medical costs not covered, urgent flights, job loss, a school change and enough accessible money to leave or make a new plan.
Build your monthly budget
Six costs shape what your family will spend
Price the first four using named providers. You can then adjust daily life and travel without treating essential costs as optional.
School
Exact year group, every compulsory fee
Home
Inside a tested school journey
Health
Premium plus costs not covered
Transport
The real weekday pattern
Daily life
Local and imported habits
Admin and travel
Renewals, flights and contingency
Choose a starting model
Five countries, five different budget pressures
Every card links to a complete country calculation with three spending bands and an auditable worked example.
How location shapes a Thailand family budget
Malaysia is a school-versus-capital balance
Vietnam runs on three budget lanes
Bali's bargain is shaped like a travel triangle
The Philippines budget is a network, not a postcode
Essential · preferred · difficult year
Plan for three versions of your family budget
Essential
Can we sustain it?- Confirmed lower-cost school
- Modest workable home
- Core insurance and transport
- Realistic spending on essentials
Preferred
Is this the life we want?- Preferred school and home area
- Activities and family travel
- Comfortable health provision
- Regular savings continue
Difficult year
What if several costs worsen?- Weaker income currency
- School or rent increase
- Income delay or job loss
- Medical or urgent-flight cost
Annual cost, uneven calendar
A monthly average can still cause a cash crisis
Schools, insurance, visas and leases may be billed termly, annually or in advance. Map payment dates before treating annual cost divided by twelve as available cash flow.
Illustrative timing only—replace it with the actual invoices and renewal calendar for your household.
Currency without false certainty
Keep four fields for every foreign-currency bill
- ContractThe exact amount and currency owed
- TimingInvoice date and payment deadline
- ReferenceDated conversion in your selected display currency
- StressCost if your income currency weakens before payment
SettleHappy uses the European Central Bank reference set dated 31 Aug 2026 for consistent planning comparisons. Your bank or transfer provider adds its own spread and charges, so budget from the amount that will actually leave the account.
The order matters
Build the budget in this sequence
- Choose the child-level school shortlist.Use current year-group fees, compulsory extras and likely support—not a school-wide “from” price.
- Draw the workable home area.Test the journey during term time and in difficult weather before pricing rent.
- Specify healthcare.Decide routine care, emergency hospital, specialist escalation, insurance and evacuation.
- Map status and tax.Price the lawful route for each person and keep professional advice outside the lifestyle total.
- Add life—and then stress it.Food, activities and travel come after the non-negotiables; rerun the result against income and currency shocks.
Bring the research together
Ready to turn your research into a family move plan?
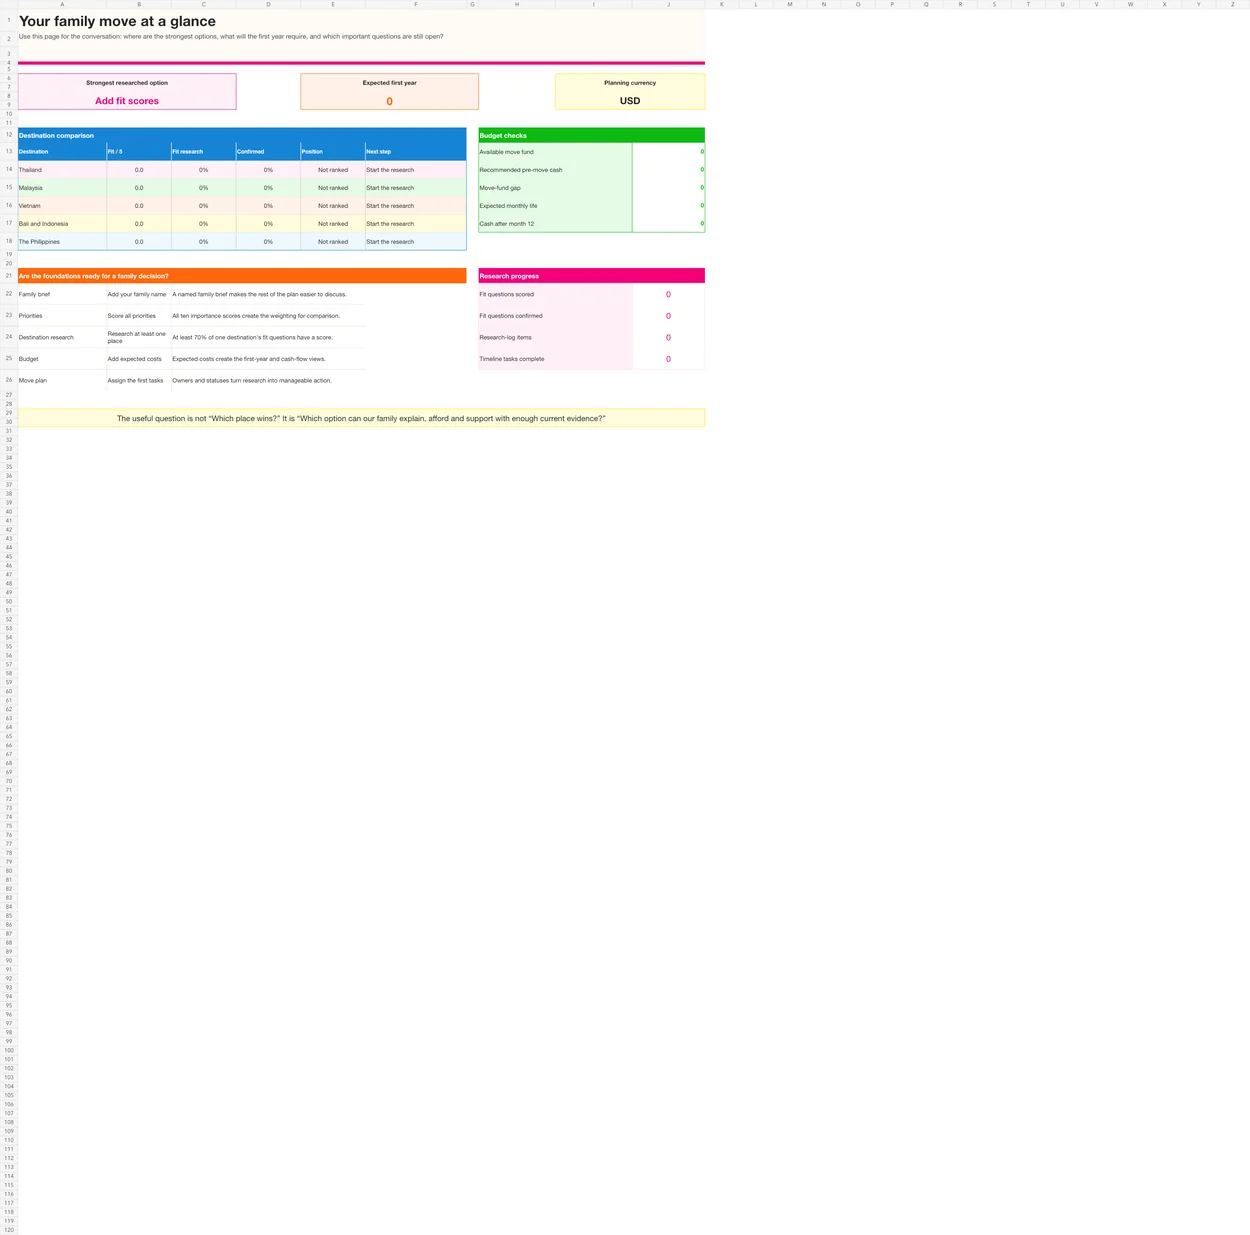
The Family Move Planner keeps your destination comparison, family priorities, budget, sources, questions and timeline in one organised system.
£39one-time digital purchase
Common questions
Questions about family relocation
How much should a family budget for Southeast Asia?
Use SettleHappy's five-country range as an outer planning envelope for two adults and two children with one international-school place. The useful answer comes from choosing a real city, school and healthcare plan rather than using the regional midpoint.
Does the budget include school fees?
Yes. Every SettleHappy country range includes one international-school place. Add a second complete school calculation for a second fee-paying child; a sibling discount rarely cancels another tuition bill.
Why should we make three budgets?
A minimum budget tests whether the move survives on restrained spending, a target budget describes the life you actually want, and a stress budget shows what happens when your income currency weakens or school, housing and health costs rise together.
Which currency should we use to compare countries?
Choose the display currency that makes the household comparison easiest, but keep every underlying contract in its billing currency. A school may bill in local currency, US dollars or a mixture, and the exchange-rate risk belongs to the currency actually owed.
How much should we hold for first-year costs?
There is no honest universal percentage. Price the actual school entry fees, rental deposit, temporary stay, flights, immigration, insurance, furniture and document work, then add a separate emergency and return reserve.
How should self-employed income be modelled?
Start with dependable after-tax household cash, not optimistic invoicing. Run a late-payment scenario, identify currencies and platform fees, and keep tax and business reserves outside the family lifestyle budget.
Can we use a digital-nomad cost estimate?
Only for individual price clues. Most nomad budgets omit children, school, larger housing, private insurance, school transport and the cost of lawful family status.
How often should the budget be updated?
Update it whenever the school schedule, lease shortlist, insurance quote, visa route or exchange rate changes. During active planning, review the complete model monthly and before paying anything irreversible.
What contingency should stay outside the destination?
Keep an accessible return reserve that is separate from everyday spending and from any visa-related fixed deposit. Its size should cover your family's plausible urgent flight, temporary accommodation in the country you would return to and transition needs.